Deutsche Bank crypto custody is moving toward a planned European launch for institutional and corporate clients in 2026. The headline sounds simple—another major bank adding Bitcoin and Ether—but the more useful question is what custody means when the asset exists on a blockchain and control depends on cryptographic keys.
Deutsche Bank says it will manage clients’ wallets and private keys, support transfers to third parties, and initially cover Bitcoin, Ether, USDC, EURC, and EURAU. The service is less like placing digital coins in a vault and more like outsourcing the systems, permissions, and signing authority needed to control blockchain-based assets.
Custody Means Controlling Access, Not Storing Coins
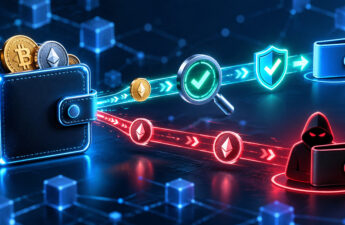
Digital-asset custody works differently from traditional safekeeping because there is no physical asset to place inside a vault. The real responsibility is controlling the credentials and systems that determine who can move assets on a blockchain.
That makes private-key management the central issue. Whoever controls the signing process can authorize transfers, which means institutional custody has to combine cryptographic security with internal approval rules, transaction monitoring, backup procedures, and access controls.
For large financial institutions, this is partly an operational problem. Many firms may want exposure to digital assets without asking employees to manage seed phrases, hardware wallets, or recovery procedures internally.
A bank custodian can take over much of that infrastructure while keeping client access subject to documented permissions and institutional controls. That is the context behind Deutsche Bank’s planned custody offering.
What Deutsche Bank Will Actually Hold
A Bitcoin does not sit inside a bank vault. The blockchain records which addresses control particular units, while private keys authorize transactions from those addresses. Protecting the key infrastructure is therefore central to custody.
Under the planned custody service, Deutsche Bank says it will manage wallets and private keys on behalf of clients. The service also includes transfers of supported assets to third parties, reducing the need for institutions to build their own custody stack.
Custody does not mean Deutsche Bank is buying Bitcoin for itself or converting a client’s crypto into a conventional bank deposit. The bank is providing the controlled access layer through which client assets can be safeguarded and moved.
For institutions, that layer includes more than a password. Deutsche Bank describes secure key generation, hardware-based protection, segregation of duties, multi-person approvals, redundant infrastructure, backup and recovery procedures, and separate warm and cold storage environments. The exact wallet structure and allocation between storage types were not disclosed.
How Deutsche Bank crypto custody Fits Among Custody Models
The clearest comparison is who controls the keys and what job the provider performs.
| Custody model | Who manages private keys? | Main operating model | Main trade-off |
|---|---|---|---|
| Bank custody | Regulated bank or its custody infrastructure | Safekeeping, controls, reporting and authorized transfers | Client relies on the custodian’s systems and procedures |
| Exchange custody | Exchange or affiliated custodian | Custody commonly sits alongside trading and account services | Convenience creates dependence on the platform’s custody structure |
| Self-custody | Asset owner | Owner manages wallet, backups and transaction signing | Maximum direct control also means direct responsibility |
Not every exchange uses the same custody structure, and institutional arrangements differ. The useful dividing line is who controls the signing process. Self-custody keeps that responsibility with the owner; third-party custody delegates it.
For institutions, delegation can solve a governance problem. An asset manager may not want one employee holding a seed phrase or a treasury team improvising backup procedures. Recent evidence around private-key exposure also shows why operational controls matter alongside blockchain security.
Cold and Warm Storage Solve Different Problems
Cold storage generally keeps signing keys offline or isolated from routine network access. That reduces online exposure but makes immediate transfers less convenient. Warm storage is designed for more accessible transaction activity, creating a different balance between availability and isolation.
Deutsche Bank says its design separates warm and cold storage environments and uses hardware-based key protection and multi-person approval processes. Those controls matter because authorization is an organizational process, not merely a cryptographic event.
A valid blockchain signature can move assets even when the organization behind it did not intend that specific transfer. Institutional custody therefore has to answer questions a blockchain cannot: Who requested the transaction? Who approved it? Were duties separated? Did the instruction pass internal limits? Can the event be reconstructed later?
That is where bank custody begins to look less like a wallet product and more like financial infrastructure.
Regulation Changes the Custody Relationship
European rules make the custody relationship more explicit than a generic promise to “keep crypto safe.” MiCA’s European custody rules require providers within scope to address custody policies, client-position records, security systems, return procedures, and segregation between client assets and the provider’s own holdings.
The rules frame custody as safeguarding or controlling crypto-assets or their means of access, including private cryptographic keys. That fits the practical reality: control of access is custody’s core function even when the asset remains recorded on a distributed ledger.
Deutsche Bank’s announcement also sets a boundary. The service remains subject to completion of the applicable regulatory timeline, while timing, geographic availability, supported assets, and service scope can change.
The bank also states that crypto-assets do not receive deposit-guarantee protection comparable with eligible bank deposits. A regulated bank custodian changes the governance and operational arrangement; it does not turn Bitcoin or a stablecoin into an insured deposit.

The Launch Details That Still Matter
The initial asset list is limited to Bitcoin, Ether, USDC, EURC, and EURAU, while tokenized financial instruments are included in the roadmap. Expansion is expected to depend on client demand, product approval, risk management, and regulatory processes.
The first target group is institutional rather than retail. Deutsche Bank identifies corporates, asset managers, hedge funds, custodians, brokers, and sovereign institutions among prospective clients from its Corporate Bank and Investment Bank businesses.
Several details will matter once the service moves from announcement to live operation: final regulatory status, first-client timing, geographic availability, supported networks, transfer workflows, and any additional assets. The bank has described its control architecture at a high level but has not published every technical or account-structure detail.
That restraint matters. Planned capability is not live availability, and institutional custody should be judged by the controls, legal structure, operational record, and service terms that exist when clients are actually onboarded.
Deutsche Bank crypto custody matters because it shows what institutional crypto adoption can look like: not a bank simply “holding coins,” but a regulated intermediary taking responsibility for wallet infrastructure, private-key management, transaction authorization, and operational controls.
The opportunity is easier access for institutions that do not want to build custody systems themselves. The pressure point is equally clear: once key control is delegated, the quality of the custodian’s governance and security becomes part of the asset’s risk profile. The launch becomes more meaningful when those planned controls move into real client operations.
Frequently asked questions
Is Deutsche Bank’s crypto custody service available now?
Not yet. Deutsche Bank plans to begin serving institutional and corporate clients in 2026, but the launch remains subject to completion of the applicable regulatory process and other internal requirements.
Will Deutsche Bank own clients’ Bitcoin and Ether?
Custody does not mean the bank buys the assets for itself. Deutsche Bank plans to manage clients’ wallets and private keys, giving it responsibility for the infrastructure used to safeguard and authorize transfers.
Is bank crypto custody safer than self-custody?
The models carry different risks. Bank custody transfers key management and operational responsibilities to a regulated provider, while self-custody gives the owner direct control but also responsibility for keys, backups, and transaction security.